
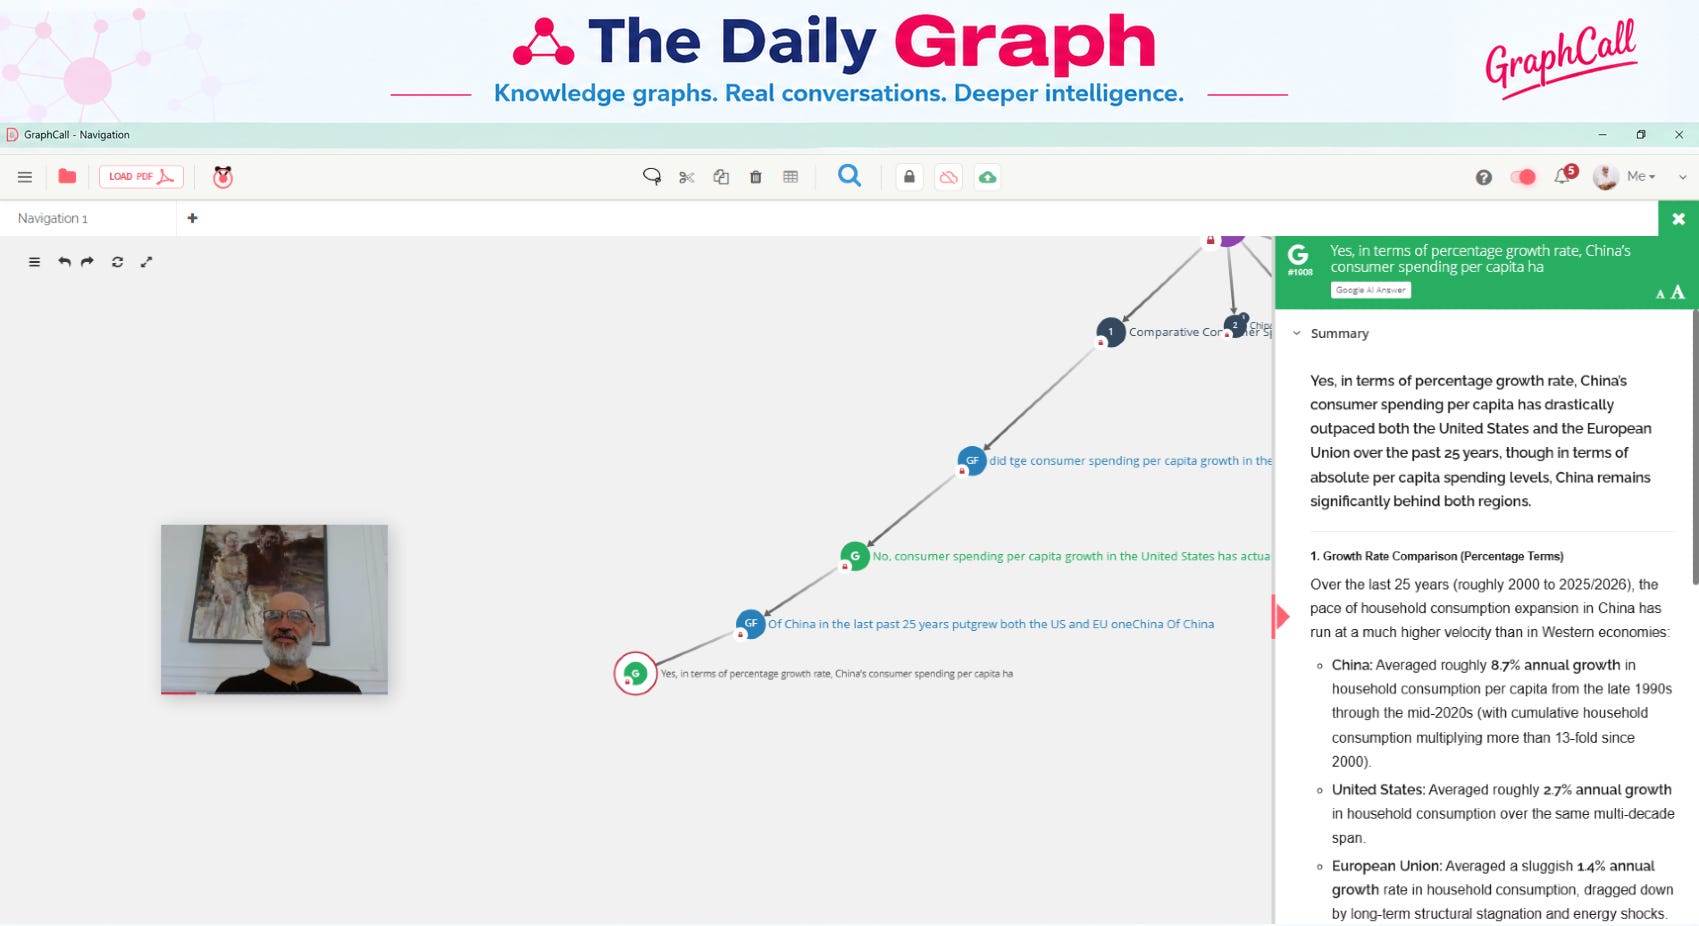
China is not Japan. Real estate, micro-credit and COVID scars are masking structural strengths. Unlike Japan, China is not recycling its trade surplus into foreign assets, while EV adoption reduces the income exported to pay for oil. Savings build productive capital, ultimately driving productivity, lower prices and rising real purchasing power. Meanwhile, China is emerging from a credit bust, while the US increasingly displays late-cycle excesses. The investment opportunity lies in recognising

Rising geopolitical tensions may weaken dollar recycling as Gulf states deepen ties with Beijing, keeping base rates higher. This comes as private credit—now a key absorber of capital—shows growing stress. Higher funding costs, redemption limits, and valuation gaps in BDCs signal the credit cycle is turning. With inflows slowing and capital absorption weakening, the system is entering a late-cycle phase where credit expansion stalls and pricing begins shifting from models to market reality.

From the 17th century, Caribbean sugar fueled European wealth via plantations reliant on enslaved labor. Napoleonic Wars, slave revolts, and embargoes disrupted trade, while Europe’s sugar beet offered a cheaper, local alternative. Similarly, today EVs, renewables, and local energy reduce dependence on oil and natural gas, slashing costs and reshaping global energy markets—history repeating itself in technological disruption.
"US NIIC deficit worsens as renewables threaten petrodollar demand. Why Trump's anti-EV stance links to foreign capital dependency. Data-driven analysis.